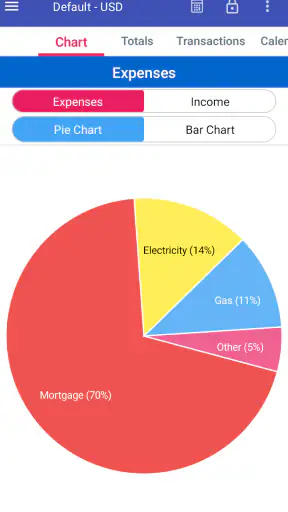
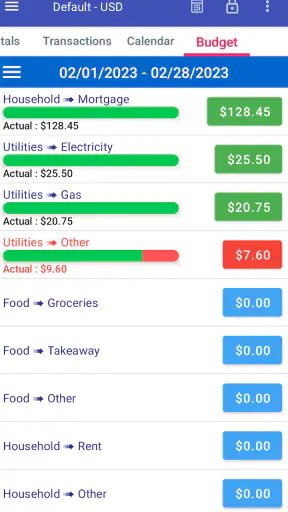
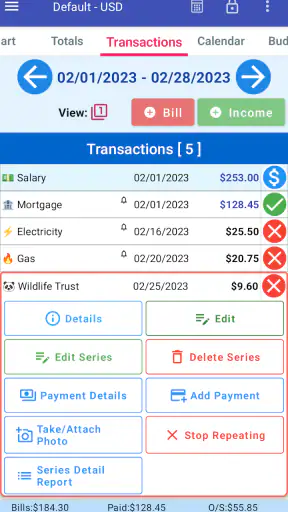
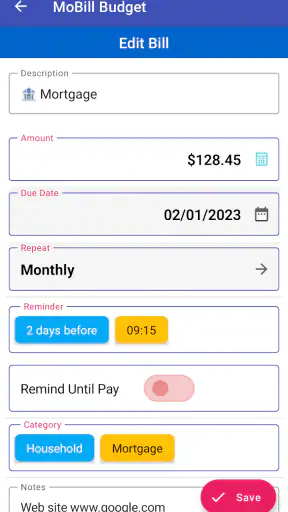
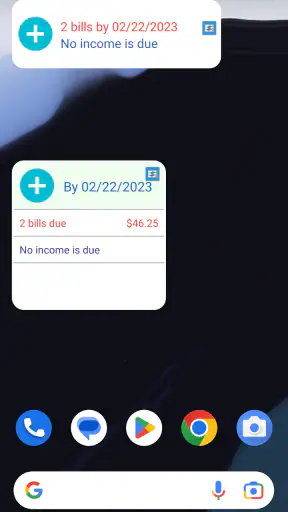
I usually notice a finance app’s value on an ordinary Tuesday, not while setting it up. A bill arrives, a subscription renews, and a small purchase slips through the day. MoBill Budget and Reminder is built around preventing that quiet loss of control. It is a free finance app from MoBill Apps that combines personal budgeting with reminders, and its most useful idea is simple: a budget becomes more practical when it is connected to the moment a payment needs attention.
After spending time with it, I see the app as a focused tool rather than a complete financial command center. It does not try to replace every banking or investment service. Instead, it gives people a place to think ahead about regular expenses and keep daily spending within a plan. That makes it particularly appealing if your main problem is forgetting due dates or treating a monthly budget as an abstract number.
Why the reminder capability changes the budget experience
Many budgeting tools are good at showing what has already happened. They organize transactions, draw charts, and summarize spending after the money is gone. That is useful, but it can leave a gap between understanding your finances and acting on them. MoBill Budget and Reminder puts more attention on the next payment, which changes the rhythm of using the app.
The practical effect is that a recurring expense becomes something I can prepare for instead of something I discover later. A bill is not only a line in a budget; it is also an upcoming obligation that deserves a place in my routine. That distinction matters when several payments arrive close together. Even a modest expense can cause trouble if it is forgotten at the wrong time.
I find this approach more approachable than a system that expects me to study financial reports every day. The app’s purpose is easier to understand: record the commitments that matter, keep them visible, and use reminders to make the budget actionable. For someone who wants a calmer monthly routine, that narrow focus is a strength.
It is also why I would not describe this as an automatic financial analyst. The app is most valuable when I actively maintain it. If I enter a payment incorrectly or fail to update an amount, the reminder can still be punctual while the plan itself is inaccurate. The tool supports good habits; it does not create them without participation.
Turning recurring expenses into a routine
The best way to use the app is to treat reminders as part of a weekly money check rather than as isolated alerts. I would begin with expenses that are easy to overlook: household bills, memberships, school-related payments, insurance, or any regular charge that competes with everyday spending. Once those obligations are visible, I can judge what remains available for flexible purchases.
This creates a useful separation between money that is already committed and money that can be used freely. A budget often fails when both types are treated as one pool. By giving future payments their own attention, MoBill Budget and Reminder helps me avoid spending money that only appears to be available.
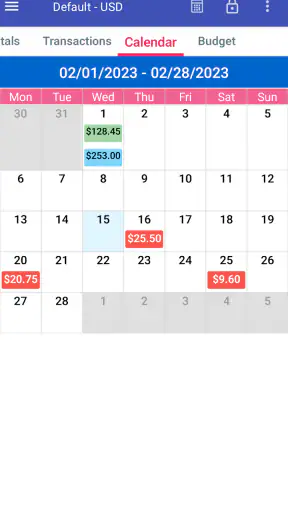
There is a subtle advantage here for people whose income and bills do not line up neatly. If several obligations fall near the same point in the month, the reminder view can encourage earlier preparation. I can check the upcoming commitments before making a larger discretionary purchase, instead of reacting after the account balance has become uncomfortable.
My advice is to keep the reminder list meaningful. Adding every tiny purchase would make the system noisy and reduce the importance of the alerts. I would reserve it for payments that are recurring, costly enough to affect the plan, or easy to miss. That small bit of discipline makes the feature more useful than simply filling the app with entries.
How I would use it during a normal month
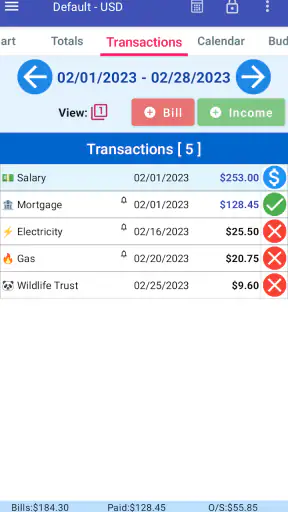
Imagine a household where payday arrives near the start of the month, while several bills are scheduled later. The person using the app can review the expected commitments first, then decide how much room is left for groceries, transport, entertainment, and unexpected costs. When a reminder appears, it is not a surprise; it is a prompt to confirm that the payment is still accounted for.
That workflow is especially helpful for someone who tends to remember bills only when an email or paper notice appears. The app gives the user a deliberate place to think about the expense before the deadline. It also makes a monthly budget feel less like a single target and more like a series of decisions spread across the calendar.
I would use the same method for annual or irregular obligations, provided I was willing to enter them carefully and revisit the plan. The important insight is not to wait until a payment is close. A reminder has the greatest value when it gives enough time to adjust other spending, move money aside, or question whether the expense still belongs in the plan.
For shared household finances, the app can also serve as a personal reference point, but I would be cautious about treating it as a live shared ledger unless everyone involved follows the same updating routine. A budget entry is only as reliable as the person maintaining it. That is a practical limitation, not a flaw unique to this app, but it matters when more than one person spends from the same pool.
Where it fits among finance alternatives
Compared with a notebook or a basic spreadsheet, MoBill Budget and Reminder is more convenient for keeping payment prompts close to the budget itself. A spreadsheet can be more flexible, especially for detailed categories and custom calculations, but it usually depends on manually checking dates or building a separate reminder system. This app’s appeal is that the planning and prompting belong in the same place.
Compared with a bank application, it offers a different perspective. A bank app is usually the authoritative place to see actual balances and completed transactions. MoBill is better suited to personal planning, especially when I want to think about upcoming commitments rather than merely inspect the account after activity has occurred. I would use the two for different jobs instead of expecting one to replace the other.
More advanced finance platforms may be preferable for people who want automatic transaction imports, investment tracking, household collaboration, detailed reports, or sophisticated account synchronization. MoBill Budget and Reminder makes more sense for someone who values a direct, manually controlled system. The trade-off is clear: less complexity can mean less automation.
That simplicity may also be reassuring for users who do not want to connect every financial account to a budgeting service. At the same time, manual entry requires consistency. If you want a system that builds its picture of your finances automatically, this is probably not the first option I would choose.
The small details that determine whether it works
The app is free to install, with in-app purchases ranging from $2.50 to $10.99 per item. I would start with the free experience and judge it by one question: does it help me remember meaningful obligations without adding more work than the problem itself? That is a better test than collecting every available budgeting feature.
Its content rating is Everyone, which fits the straightforward nature of a personal finance and reminder tool. The current version is 5.3.1, and the app requires Android 8.0 or later. That minimum requirement is worth checking before planning to use it on an older Android device.
The app has been available since February 28, 2011, and its audience has grown to over 500 thousand installs. It holds a 4.0 average from around 3.8 thousand ratings, alongside roughly 1.6 thousand written reviews. Those figures suggest a product with a substantial usage history, while also reminding me that it is not universally perfect for every budgeting style.
I would pay attention to the difference between a reminder and a confirmation. A notification can tell me that a bill is approaching, but it cannot by itself prove that the payment was made or that the amount remained unchanged. My own routine would be to mark the budget mentally or in the app after checking the real account, rather than assuming the reminder completes the task.
Another useful habit is to review entries after a change in living arrangements. Moving, changing providers, canceling a membership, or switching payment schedules can make an old reminder misleading. The app works best when I treat the list as a living plan, not an archive that can be set once and forgotten.
Who gets the most value from this focused approach
I would recommend MoBill Budget and Reminder to a person who has a fairly understandable financial situation but struggles with timing. That could be a student managing recurring expenses, a freelancer trying to organize uneven months, or a household member who wants a visible list of commitments before spending the remainder of the budget.
It is also a good fit for people who prefer entering information themselves. Manual control can make the budget feel more deliberate because I must decide what matters and how it should be categorized. For some users, that involvement is exactly what encourages awareness rather than passive dependence on automatic summaries.
The app is less suitable for someone who wants a full financial dashboard. If your priority is investment performance, automatic bank synchronization, tax organization, detailed shared accounts, or extensive visual analysis, I would look for a more specialized service. MoBill’s strength is not breadth; it is the connection between planned spending and timely reminders.
I would also skip it if I know I will not maintain the entries. A reminder system that contains old amounts or canceled expenses can create false confidence. In that situation, a bank’s live transaction history may be more dependable for checking what has actually happened, while a calendar may be enough for a small number of simple due dates.
My practical setup advice
When starting, I would avoid trying to reconstruct an entire financial history. Begin with the next group of important obligations and one realistic spending limit. This keeps the first session manageable and lets me see whether the reminder cycle fits my habits. Once that routine feels natural, I can add less frequent expenses.
I would also review the plan at the same point each week. The review does not need to be long. I would check what is approaching, compare it with the actual account, and adjust anything that has changed. This turns the app from a passive notification source into a short planning ritual.
A further tip is to use the budget as a decision boundary, not a punishment. If an unexpected expense appears, the useful response is to revise the remaining plan rather than ignore the app because the original target no longer works. A manually managed tool is most helpful when it reflects real life instead of pretending every month will follow the first estimate.
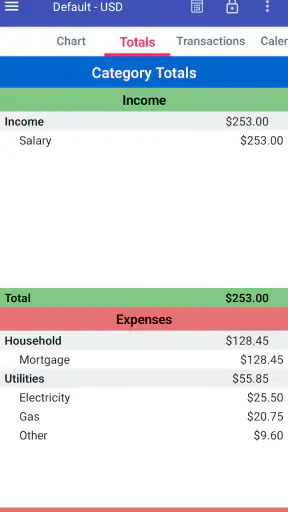
Finally, I would keep categories understandable. Overly precise labels can make entry tiring and encourage me to stop using the system. A smaller set of meaningful groups makes it easier to see which commitments are fixed and where I still have flexibility. That balance is more important than creating a perfect financial model.
My verdict after using its central idea
MoBill Budget and Reminder succeeds because it addresses a common financial failure at the right moment: forgetting what is coming next. The combination of budgeting and reminders makes future obligations visible before they compete with everyday spending. I appreciate that it can be used as a focused personal tool without forcing me into an elaborate financial workflow.
Its limits are equally clear. The value depends on accurate, regular manual upkeep, and users looking for automatic account data or advanced financial analysis may outgrow it quickly. The in-app purchase range also means that anyone considering paid options should decide whether the extra convenience genuinely improves their routine.
For me, the app is worth recommending to a friend who says, “I can afford my bills, but I keep forgetting when they are due.” It is less convincing for someone who wants every account, transaction, and long-term financial goal managed automatically. If your main need is a simple, personal way to connect planned spending with timely prompts, this is where MoBill Budget and Reminder earns its place.
In short, I would approach it as a practical reminder-centered budget rather than a replacement for a bank or a complete financial suite. Set it up with only the commitments that matter, check it regularly against reality, and let it guide decisions before money is spent. Used that way, this free Finance app from MoBill Apps offers a straightforward path toward fewer forgotten payments and a clearer view of what the month can actually support.


